Here’s something that should change how every climate founder and investor reads the market right now.
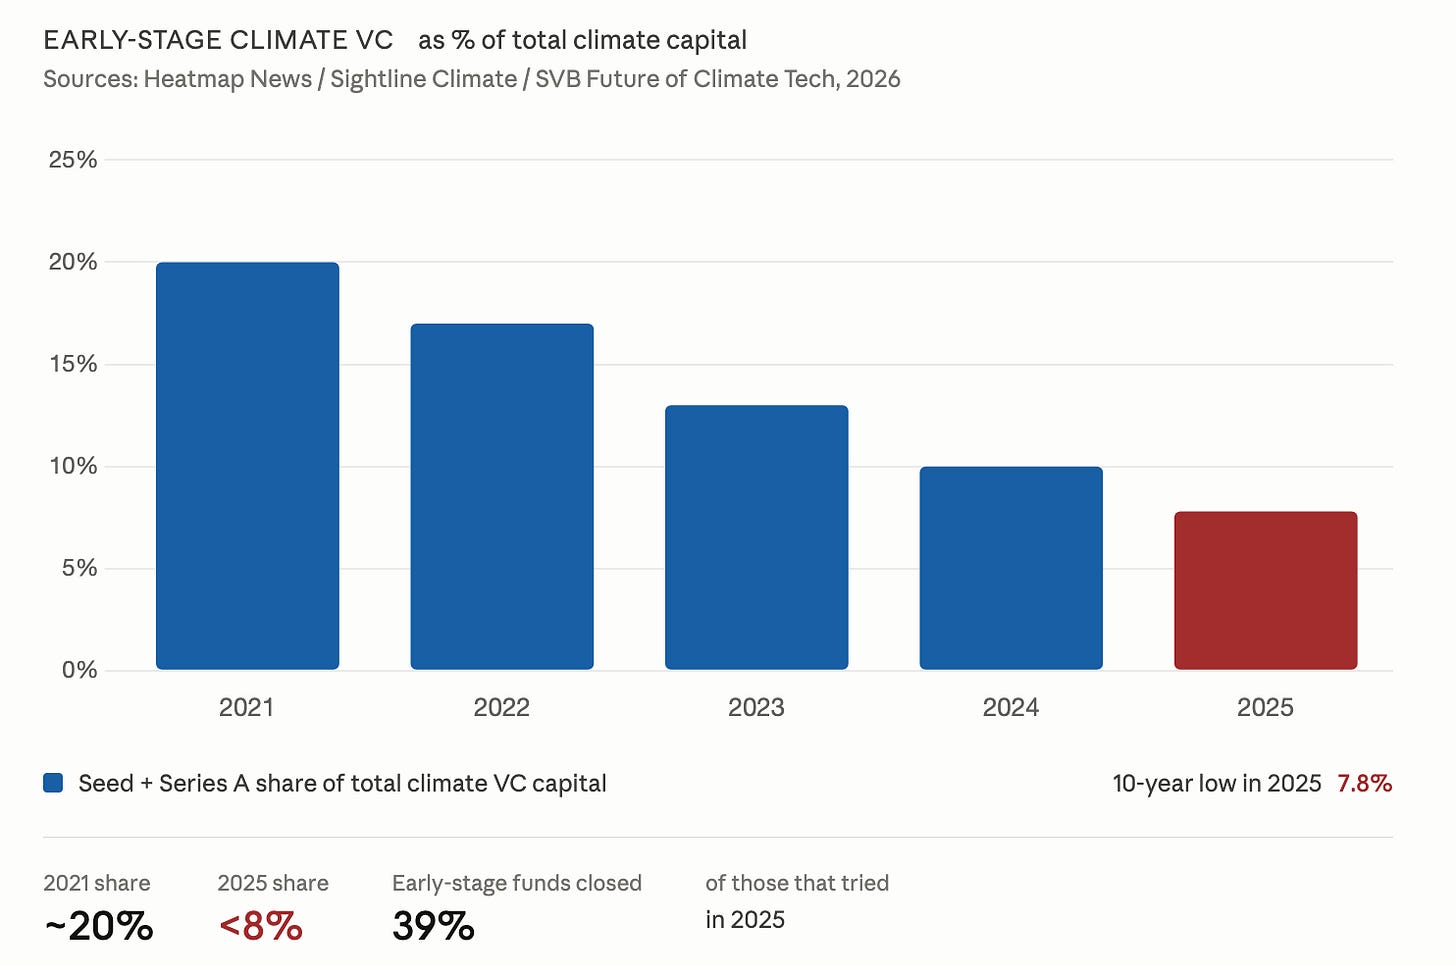
Climate tech VC hit $40.5 billion globally in 2025.
That’s an 8% increase. Growth. Momentum. Good news, right?
Here’s the other number: deal count fell 18% — to 1,545 transactions. The lowest since 2020.
More money. Fewer deals.
Average round size: $61.5 million.
The capital didn’t leave climate tech. It concentrated. And where it concentrated tells us almost everything about where the opportunity, and the friction, lives in 2026.
Where the money actually went
Energy storage and batteries absorbed more cumulative capital than any other climate subsector, $11 billion and counting. Grid-scale sodium-ion, long-duration storage, and battery management systems are all attracting serious institutional attention.
Nuclear and geothermal surged, not because of a policy breakthrough, but because of AI. Data centres consumed 78% of built-environment climate funding in 2025. Hyperscalers need clean, reliable baseload power that solar and wind alone can’t deliver at the scale and reliability they need. Fervo Energy’s IPO filing in January 2026, after a $462M Series E, put next-gen geothermal on the mainstream map.
Europe vs the US: this is the shift most founders haven’t fully absorbed. Europe now commands 54% of new climate fund capital. The US dropped to 16%. Energy Impact Partners closed their $1.36B Fund III last October. Germany’s DTCF is deploying up to €1B into climate and deep tech. The LP appetite in Europe is structurally different, and right now, more active.
What this means for founders
The playbook that worked in 2022 – “early stage, big vision, large TAM” – is not the playbook that’s working in 2026.
Investors are writing bigger checks into companies with proven technology or clear de-risked milestones, revenue or credible off-take agreements, infrastructure or grid-scale relevance, and founders who understand both policy and commercial dynamics.
Federal funding cuts hit parts of the carbon removal sector hard. The IRA still holds, but the grant landscape is more competitive. The founders getting meetings right now aren’t necessarily the ones with the best technology. They’re the ones with the sharpest market positioning.
“We’re solving carbon” doesn’t cut through.
“We sit at the intersection of AI data centre energy demand and grid scarcity – and we have an LOI with a utility” opens doors.
If your sector isn’t on this list
The sectors above are where the largest pools of VC capital are concentrating right now. But that’s not the whole picture, and it’s definitely not the whole opportunity.
Here’s what the concentration trend actually creates: less competition for investor attention everywhere else.
The funds chasing AI-energy deals are oversubscribed and moving fast on a narrow set of bets. That leaves a meaningful gap of investors – particularly in Europe, impact-first LPs, corporate venture arms, and family offices – who are actively looking for differentiated deals outside the crowded categories.
A few things worth knowing if you’re building outside the hot sectors:
The IRA still supports a broad range of clean energy and climate solutions. Grants, loan guarantees, and tax credits aren’t gone – they’re just less discussed. If you haven’t mapped your eligibility recently, it’s worth doing.
Corporate strategics are often more relevant than VC for founders in sectors like sustainable food, water, biodiversity, and circular economy. They move differently, but they’re writing cheques.
The “unfashionable” angle can actually be a pitch. Investors who are tired of seeing the same grid storage deck will sit up for a founder who comes in with a clear market, real customers, and no competition for their attention.
The fundamentals haven’t changed: strong positioning, a credible path to revenue, and the right room. The right room just looks different depending on what you’re building.
The capital hasn’t left. It’s just moved somewhere more specific.
Here’s the good news
The long-term trajectory looks good. The climate tech market is on course to reach $79.45 billion by 2029 – a compound annual growth rate of 25%. At the sector level, year-on-year growth is running at 4.33% and accelerating. The market you’re building for is getting bigger, not smaller.
Still worth building
Step back from the metrics and timeline for just a moment.
You chose to work on something that matters beyond a balance sheet. The air, the water, the land, the climate that every human being on this planet depends on. That’s what you show up for every day.
Someone will breathe easier because of what you’re building. A community will be more resilient. A species will have habitat it wouldn’t otherwise have. A child born ten years from now will inherit something better.
They won’t know your name. But they’ll live in a world you helped shape.
That’s not nothing. That’s everything.
Until next week,
Marianne
Climate builder moment 🌱
The market just got more selective. Fewer deals, higher bar, more pressure on every founder conversation. That kind of environment has a way of quietly convincing you that rest is a liability.
It isn’t.
The founders who navigate hard markets aren’t the ones who worked the hardest through them. They’re the ones who stayed clear-headed enough to make good decisions when it mattered.
This week, notice where your energy is actually going – not just in your calendar, but in your body. Sleep. Movement. A meal that isn’t eaten at your desk. These aren’t indulgences. They’re how you stay capable of thinking straight when the stakes are high.
Protect your capacity. That’s not soft advice. That’s strategy.